Case Study
When NatWest decided to bring their Virtual Terminal in-house, we faced an unusual challenge: redesign a product for users we weren't allowed to speak to. No usage data, no direct customer access, just a constraint we had to turn into an opportunity.
The project was paused before reaching final UI production, so designs shown are mid-fidelity prototypes.
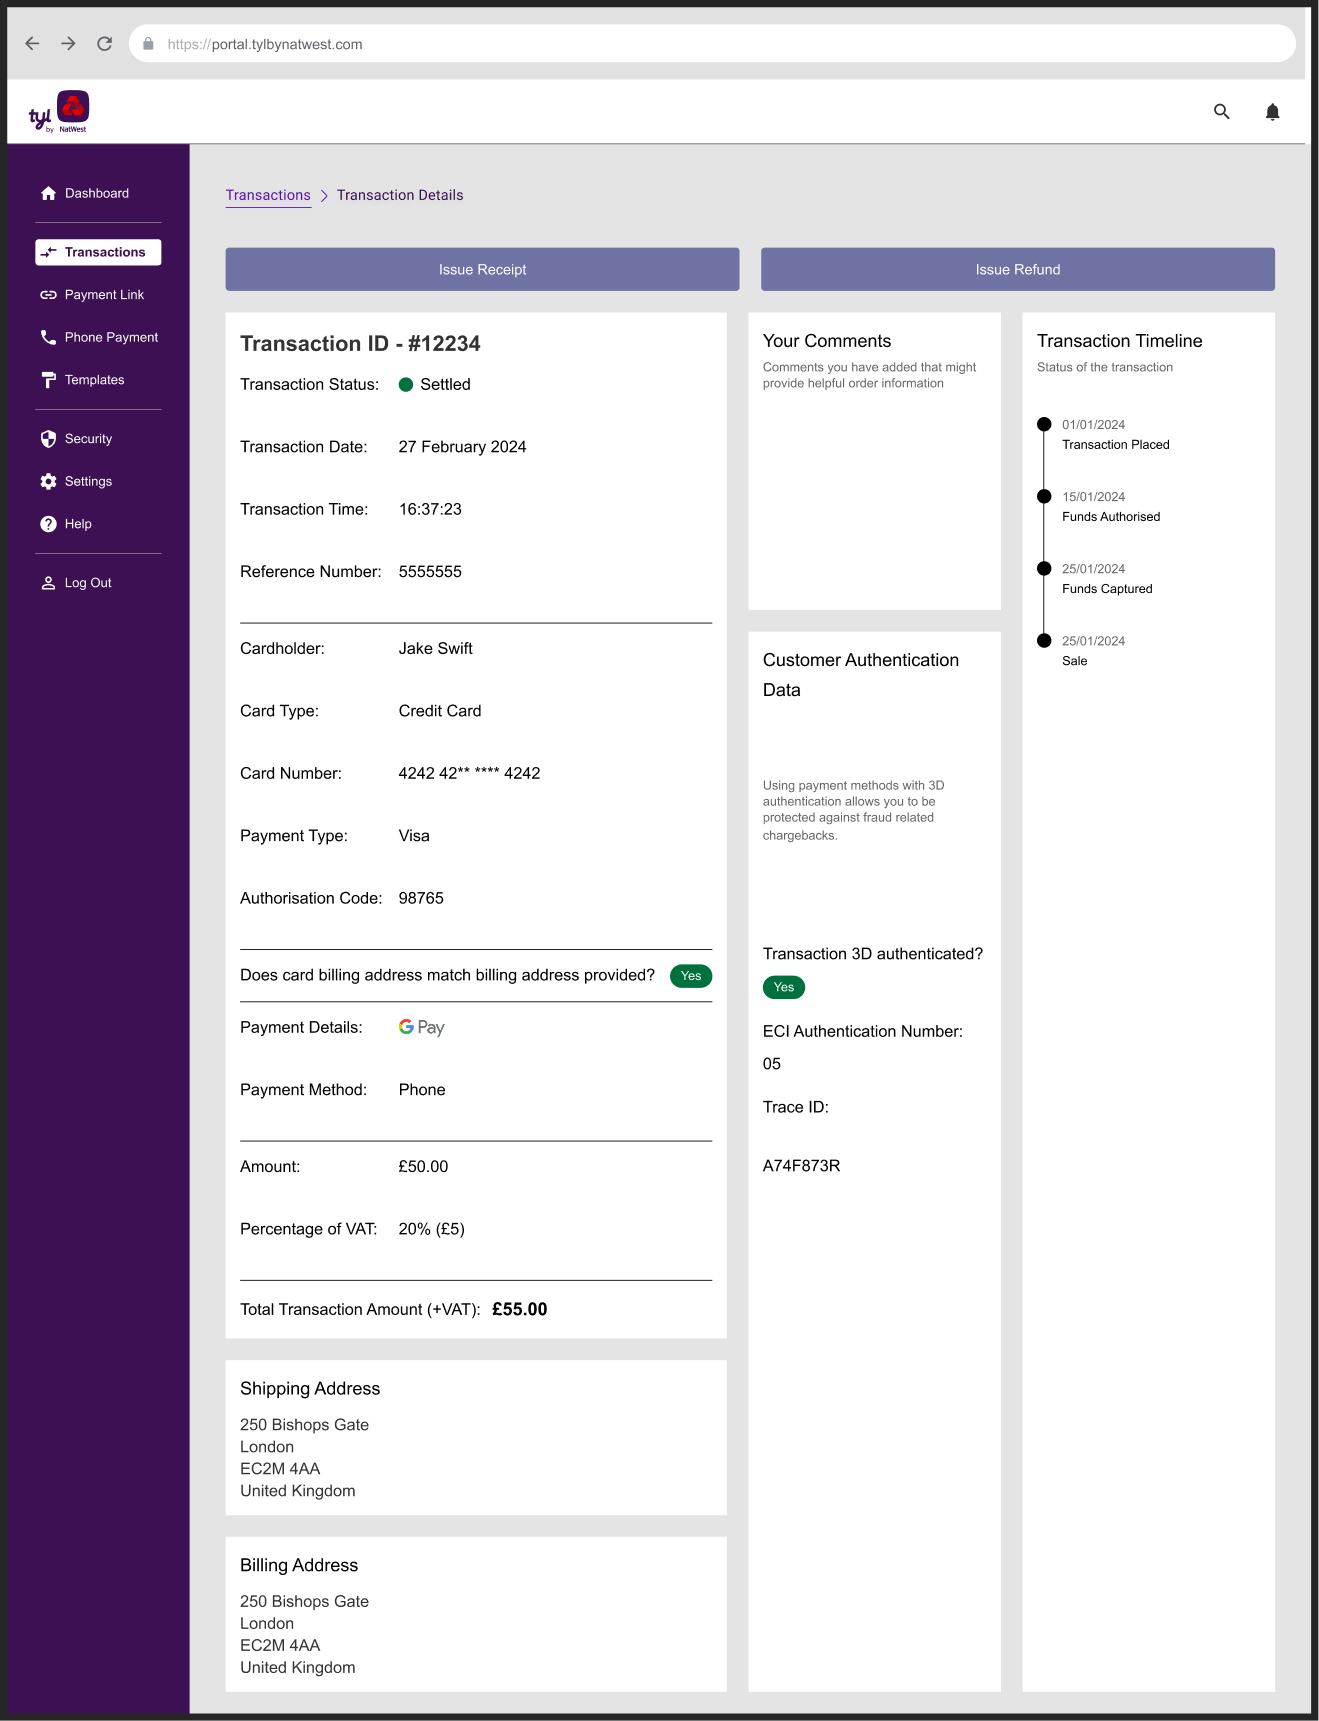
The Virtual Terminal is a payment tool used by merchants to take card-not-present payments, generate payment links and monitor transactions. It was originally built and managed by a third party as part of NatWest's Tyl offering. This meant Tyl had limited control over the product's design and experience, restricted access to customer data, and high operational costs which made it difficult to understand how merchants were using the product, where pain points existed, or how to improve the experience based on real customer needs.
Product usage data was difficult to obtain because the Virtual Terminal was managed externally. Tyl had limited visibility into how the product was being used and which customers were interacting with it. As a result, updates were largely driven by internal business or stakeholder requirements rather than insights from actual customers.
As NatWest began decoupling from this third party, it created an opportunity to redesign the Virtual Terminal and bring it fully in-house, giving the team access to product usage data, enabling direct customer feedback, and making it possible to improve the experience based on real merchant needs.
User Experience Goals
Business Requirements
Discover
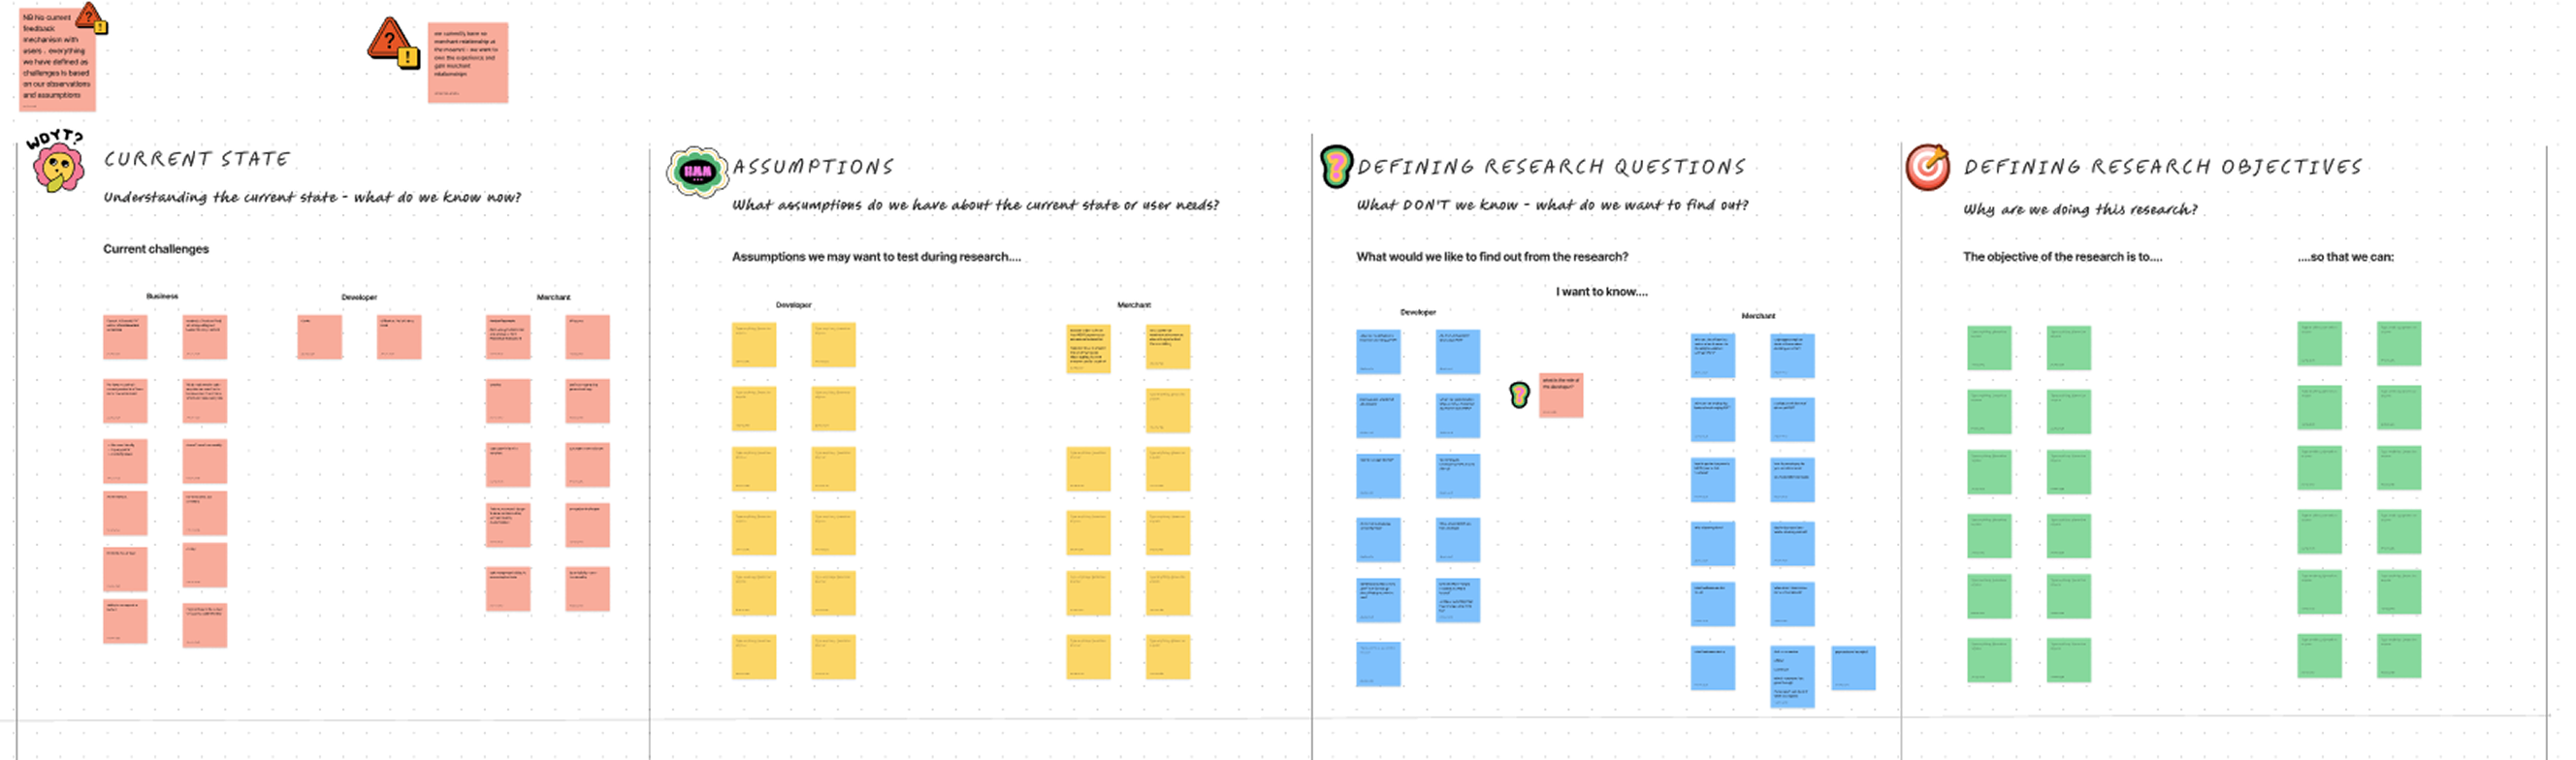
We wanted to understand how the platform was being used and where improvements were needed. Without direct access to merchants or product usage data, we ran a series of internal workshops with stakeholders, service design and research to define our target users, identify key jobs to be done, and evaluate the current experience.
Assess the current state of the product (product offering, what works well, what does not work well).
Review Virtual Terminal use cases, persona maps, outlining users of the product and understand how users engage with the product.
Review competitor propositions in the market, agree on the timeline and phases of this project.
The existing Virtual Terminal was difficult to navigate and did not follow common interface patterns.
Transaction data was presented in a confusing and overwhelming way, making reconciliation difficult.
Tyl had limited control over the product because it was built and managed by a 3rd party provider.
Accessing reporting and usage data was slow and dependent on the supplier.
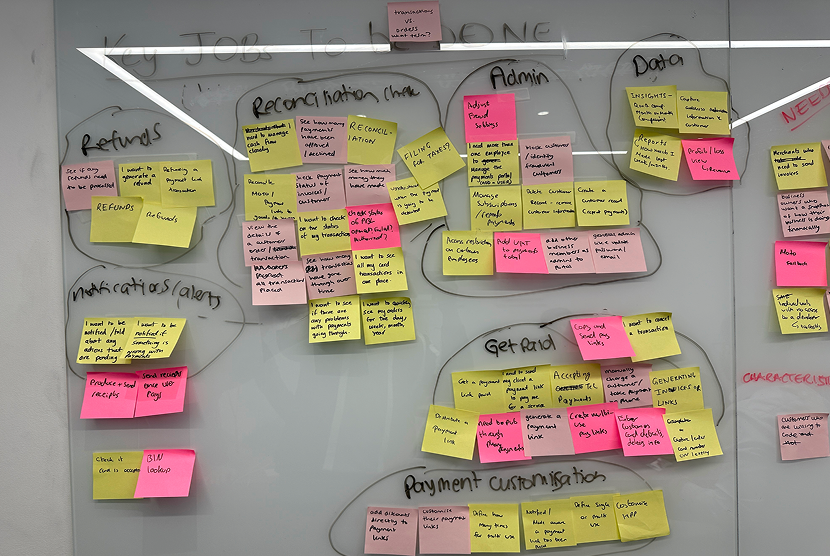
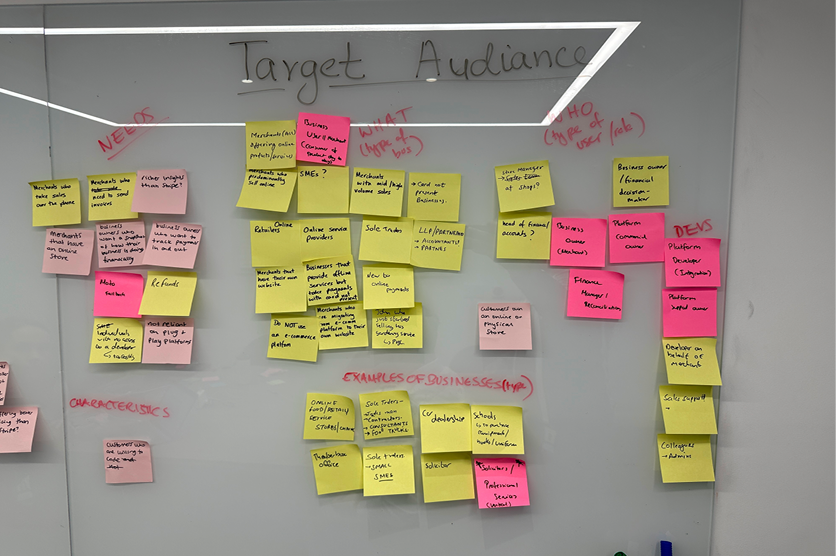
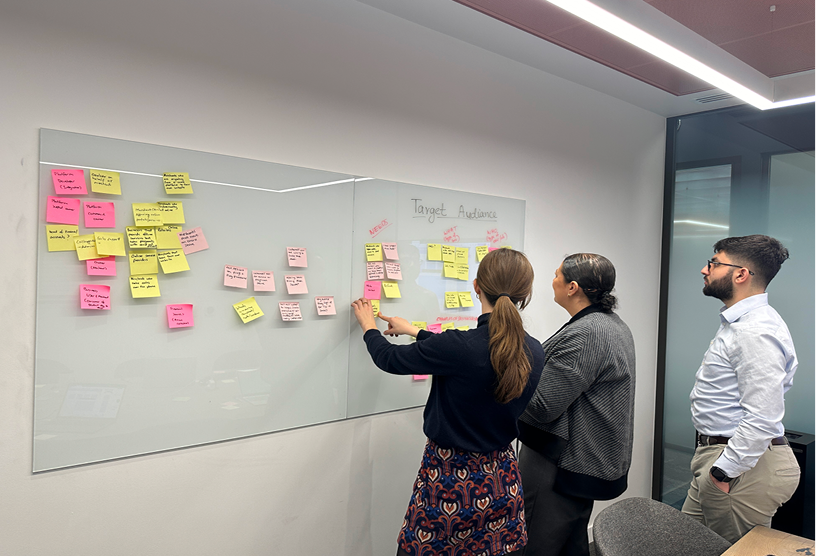
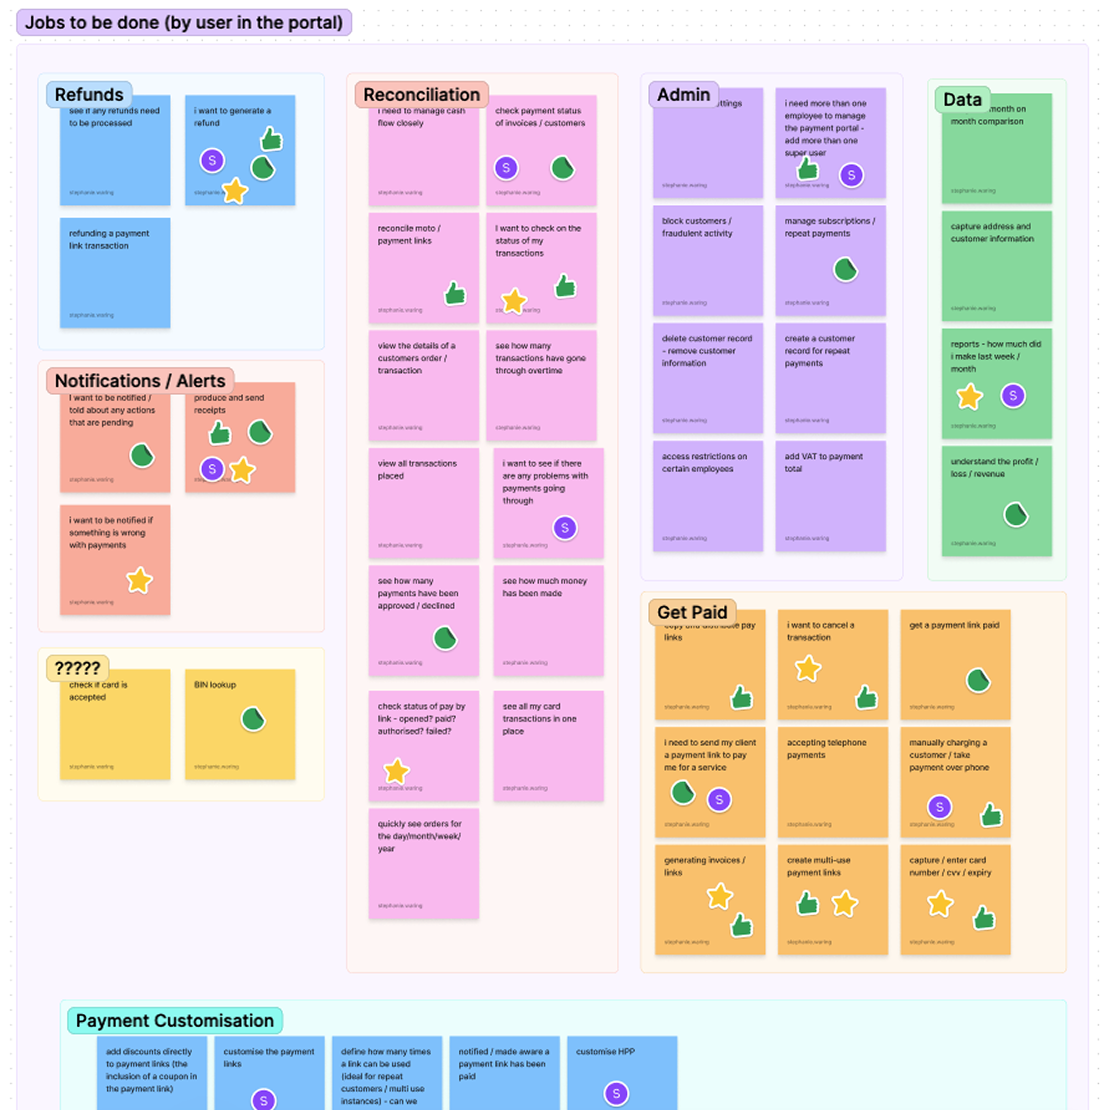
I led a second in-person workshop to further understand our customers, define key jobs to be done, evaluate the product and explore opportunities to streamline the Virtual Terminal during the redesign.
The central challenge was that we weren't permitted to speak directly to merchants using the Tyl Virtual Terminal. We had to work from stakeholder knowledge and existing NatWest personas.
This raised some important strategic questions: where does the overlap lie between the customers the business wants to target and who actually uses the product? And is this redesign intended to attract a different type of customer altogether?
Through post-it note exercises, affinity clustering and dot-voting with the team, we built a clearer picture of our typical user and ranked the jobs to be done by importance.
Small to medium-sized businesses, particularly within professional services such as solicitors, operating in card-not-present environments. They need a simple way to request and receive payments from clients, without requiring a full website or e-commerce setup.
Primary job to be done: get paid, either via a payment link or over the phone. Secondary tasks included refunds, transaction data, notifications and admin settings.
Who he is
What he needs
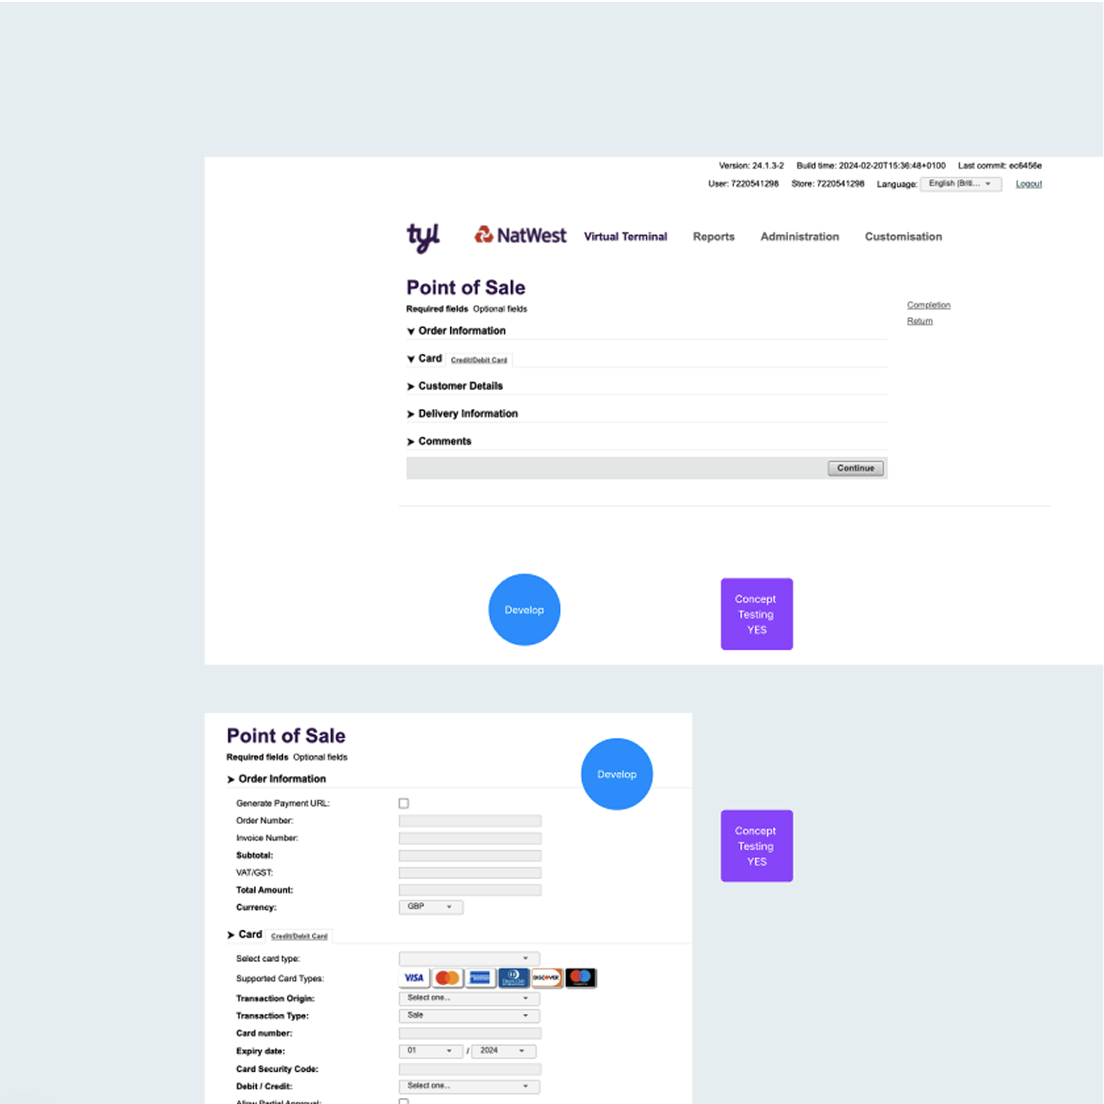
To close the workshop I prepared screenshots of the existing platform for a collaborative review.
Participants used coloured dots to indicate which pages and features should be kept, removed or further developed.
The exercise helped us prioritise key features, identify what was required for regulatory or technical reasons and surface early discussions around terminology and data points that would later inform the redesign. The insights gathered gave us a clear brief going into the first prototype.
With limited access to product data and no direct visibility into who was using the Virtual Terminal, we ran a first round of moderated usability testing with 6 micro-merchants. The goal was to understand their current payment setups, what they needed from a provider, and how they experienced the original platform.
Sessions covered four key areas:
Testing the original platform revealed a clear pattern: merchants found it confusing, outdated, and misaligned with how they actually run their businesses. These findings directly shaped the prototype.
Product-market fit gap
The VT was better suited to larger enterprises. Most micro-merchants had no need for phone payments. Pay-by-link was more relevant but still fell short.
Reframe the product scope
Prioritise pay-by-link as the primary use case. Surface its value more clearly and reduce complexity for merchants who don't need phone payment functionality.
Stripe sets the benchmark
5/6 merchants used Stripe as default, not by choice, but because it was the easiest option available. Simplicity and seamless setup were the baseline expectation.
Reduce friction at every step
Match the clarity and ease of Stripe's flows. Minimise required fields, auto-generate IDs, and remove any step that doesn't add clear value.
The dashboard should lead
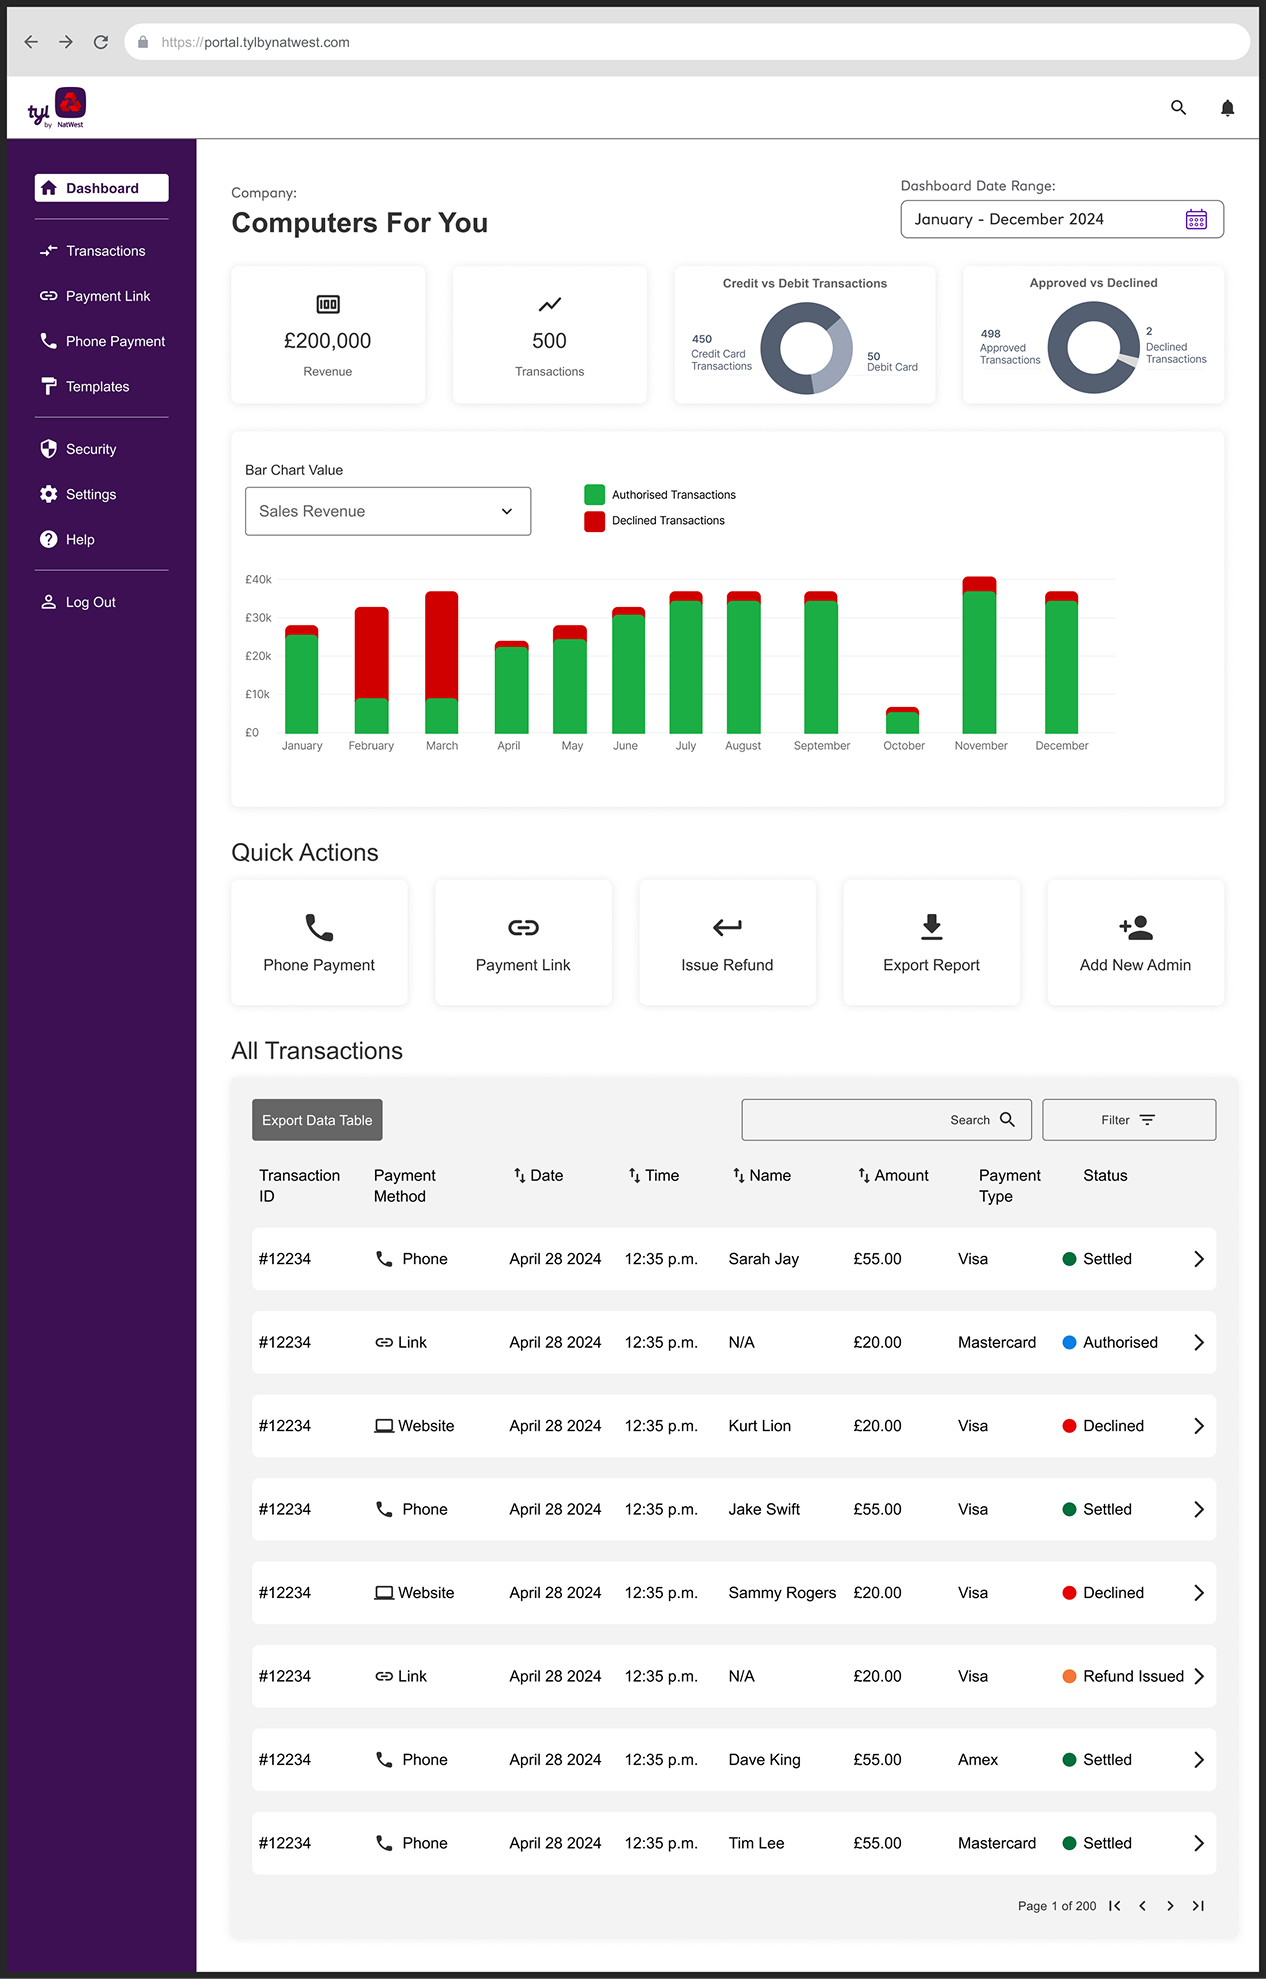
Merchants wanted sales data front and centre on login, not a payment form. They expected Shopify-style analytics, not a blank slate.
Move dashboard to default landing page
Replace the phone payment form as the entry point. Surface key metrics, recent transactions, payment status, declines, immediately on login.
Terminology caused friction
"Orders vs transactions", "payment URL", and "completion & return" consistently confused users. Merchants think in plain language.
Plain language throughout
Audit all labels and replace technical or banking terminology with merchant-familiar language. Add contextual tooltips where jargon is unavoidable.
Payment links felt untrustworthy
Auto-generated URLs looked suspicious, long, unbranded and unfamiliar. Several merchants worried their customers would think it was a scam.
Improve link credibility
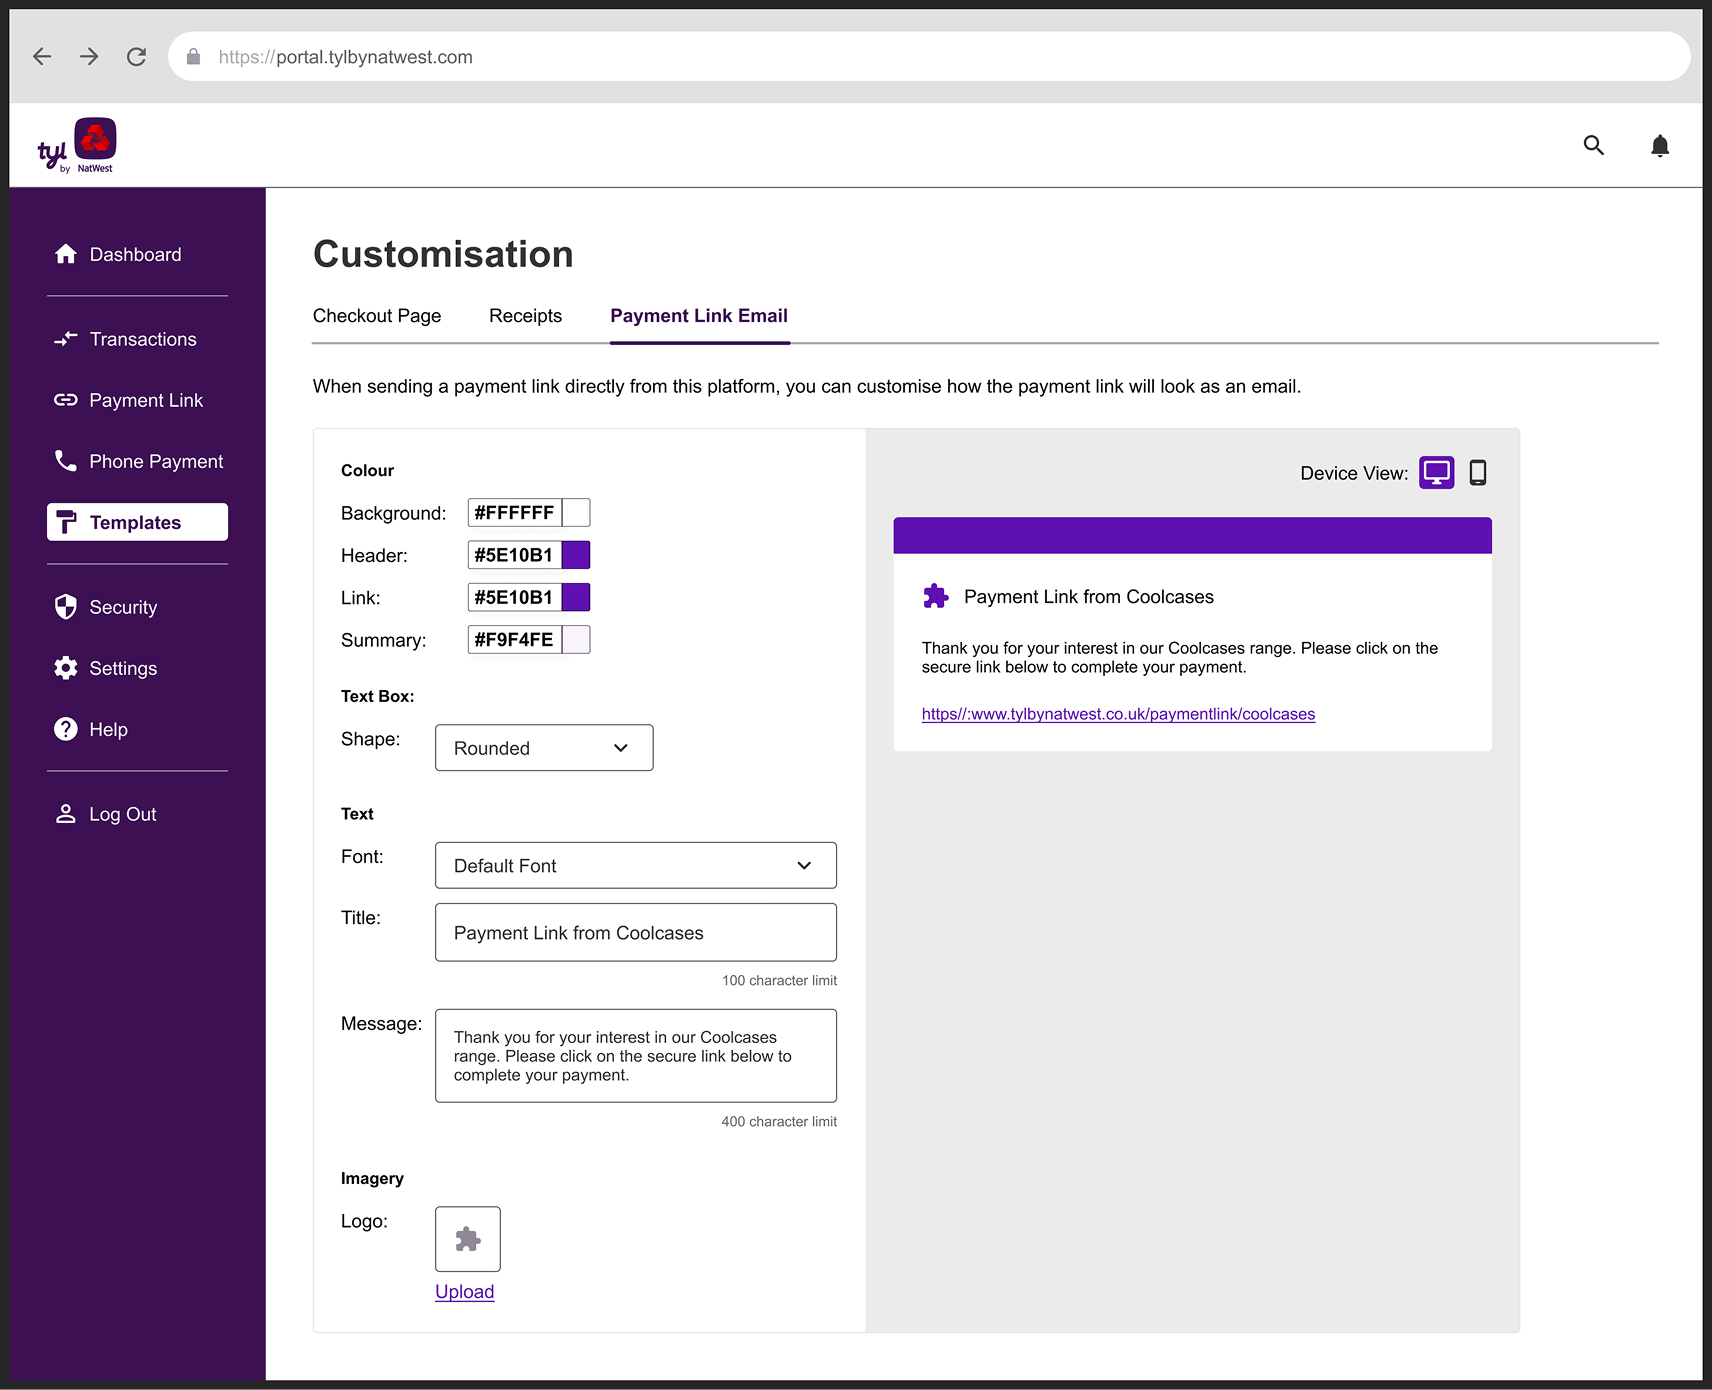
Explore branded or shortened URL options. Add a preview of how the link appears to customers before sending.
Customisation is non-negotiable
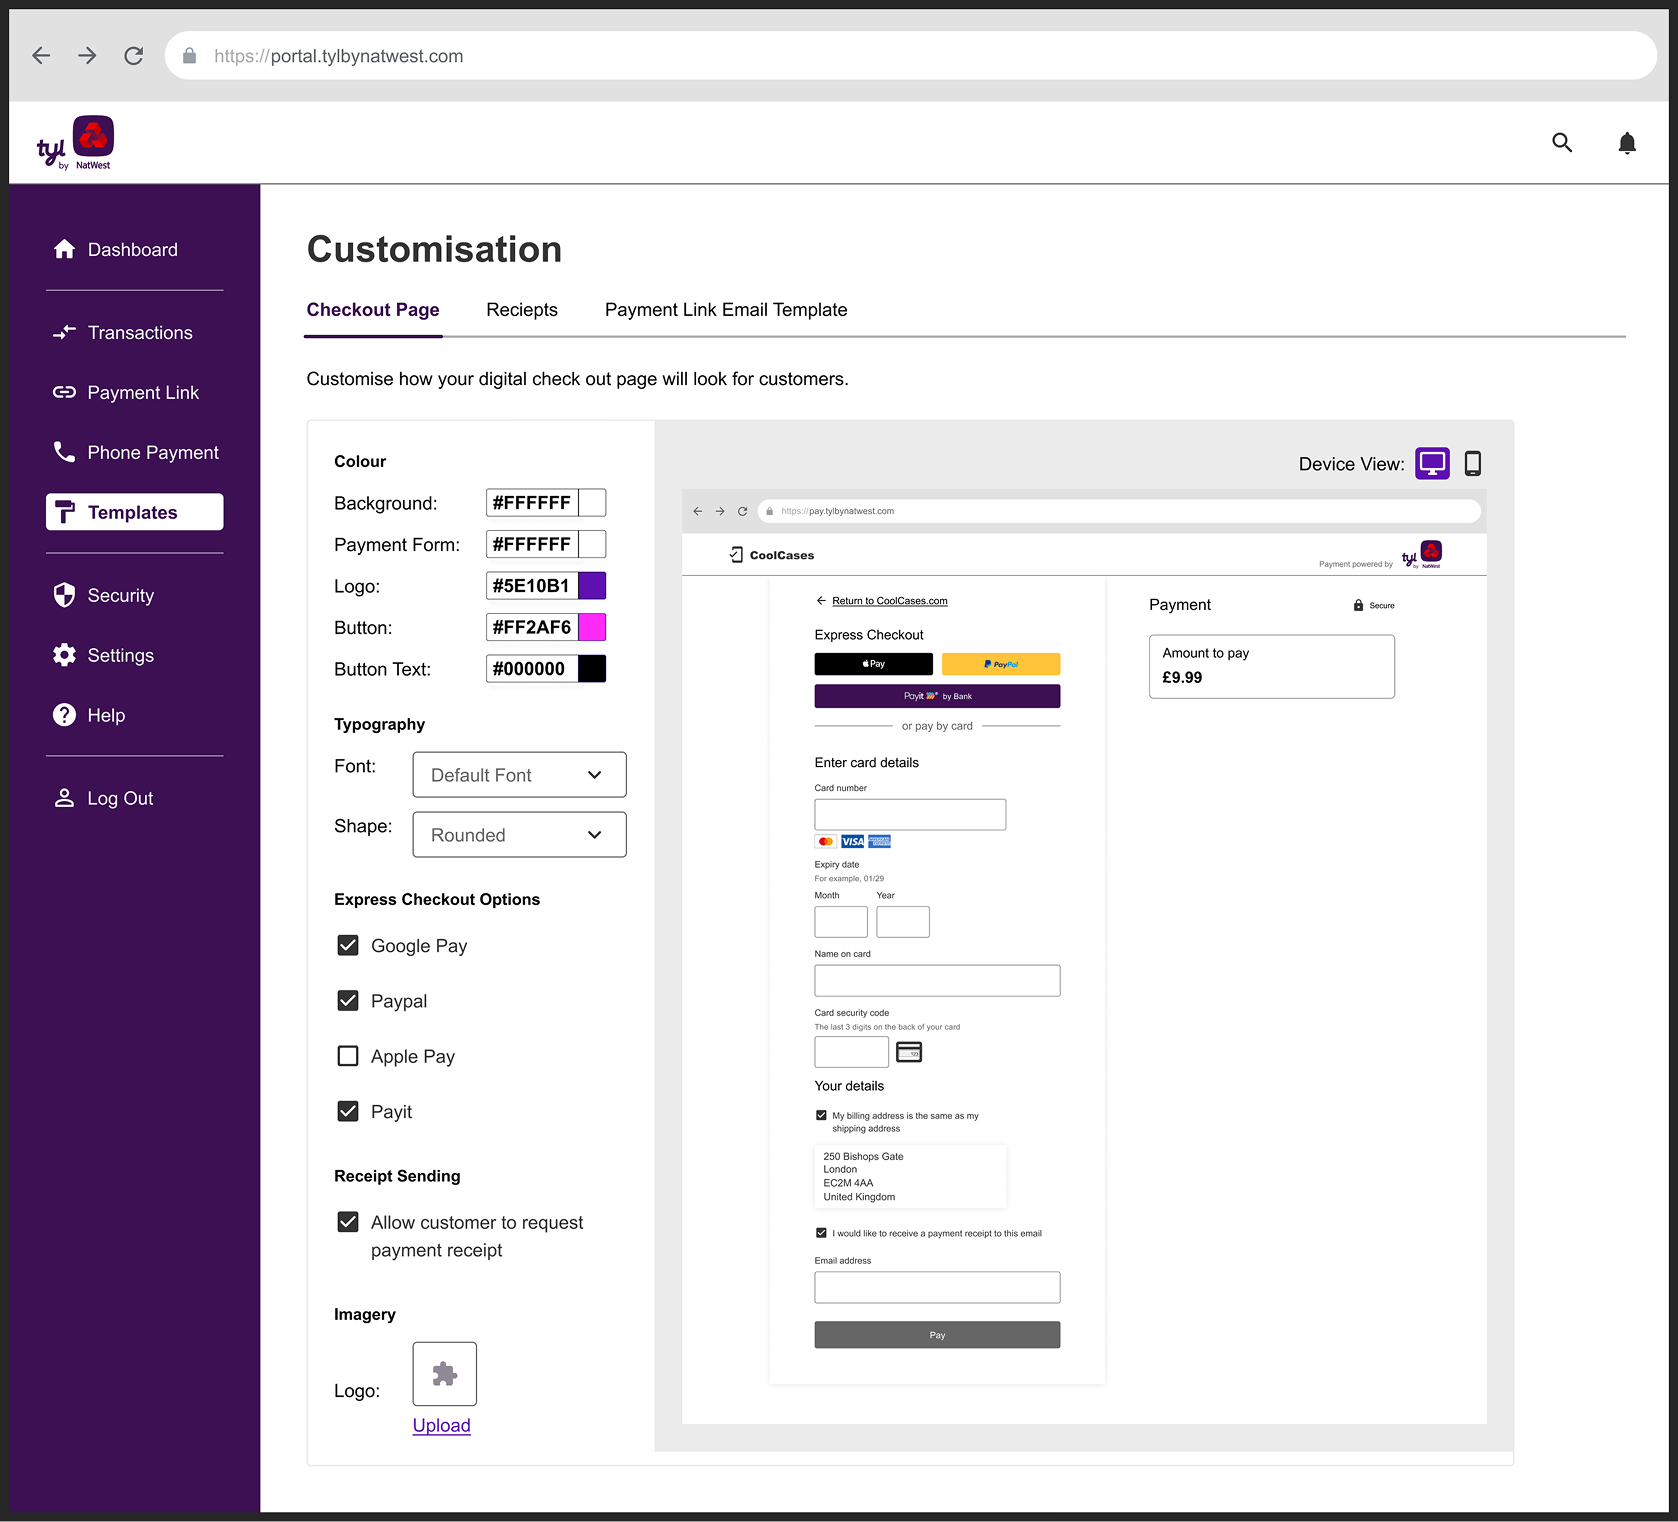
Merchants wanted branded checkouts, logo upload, and order detail fields. The generic experience felt impersonal and fell short of competitor offerings.
Build no-code customisation
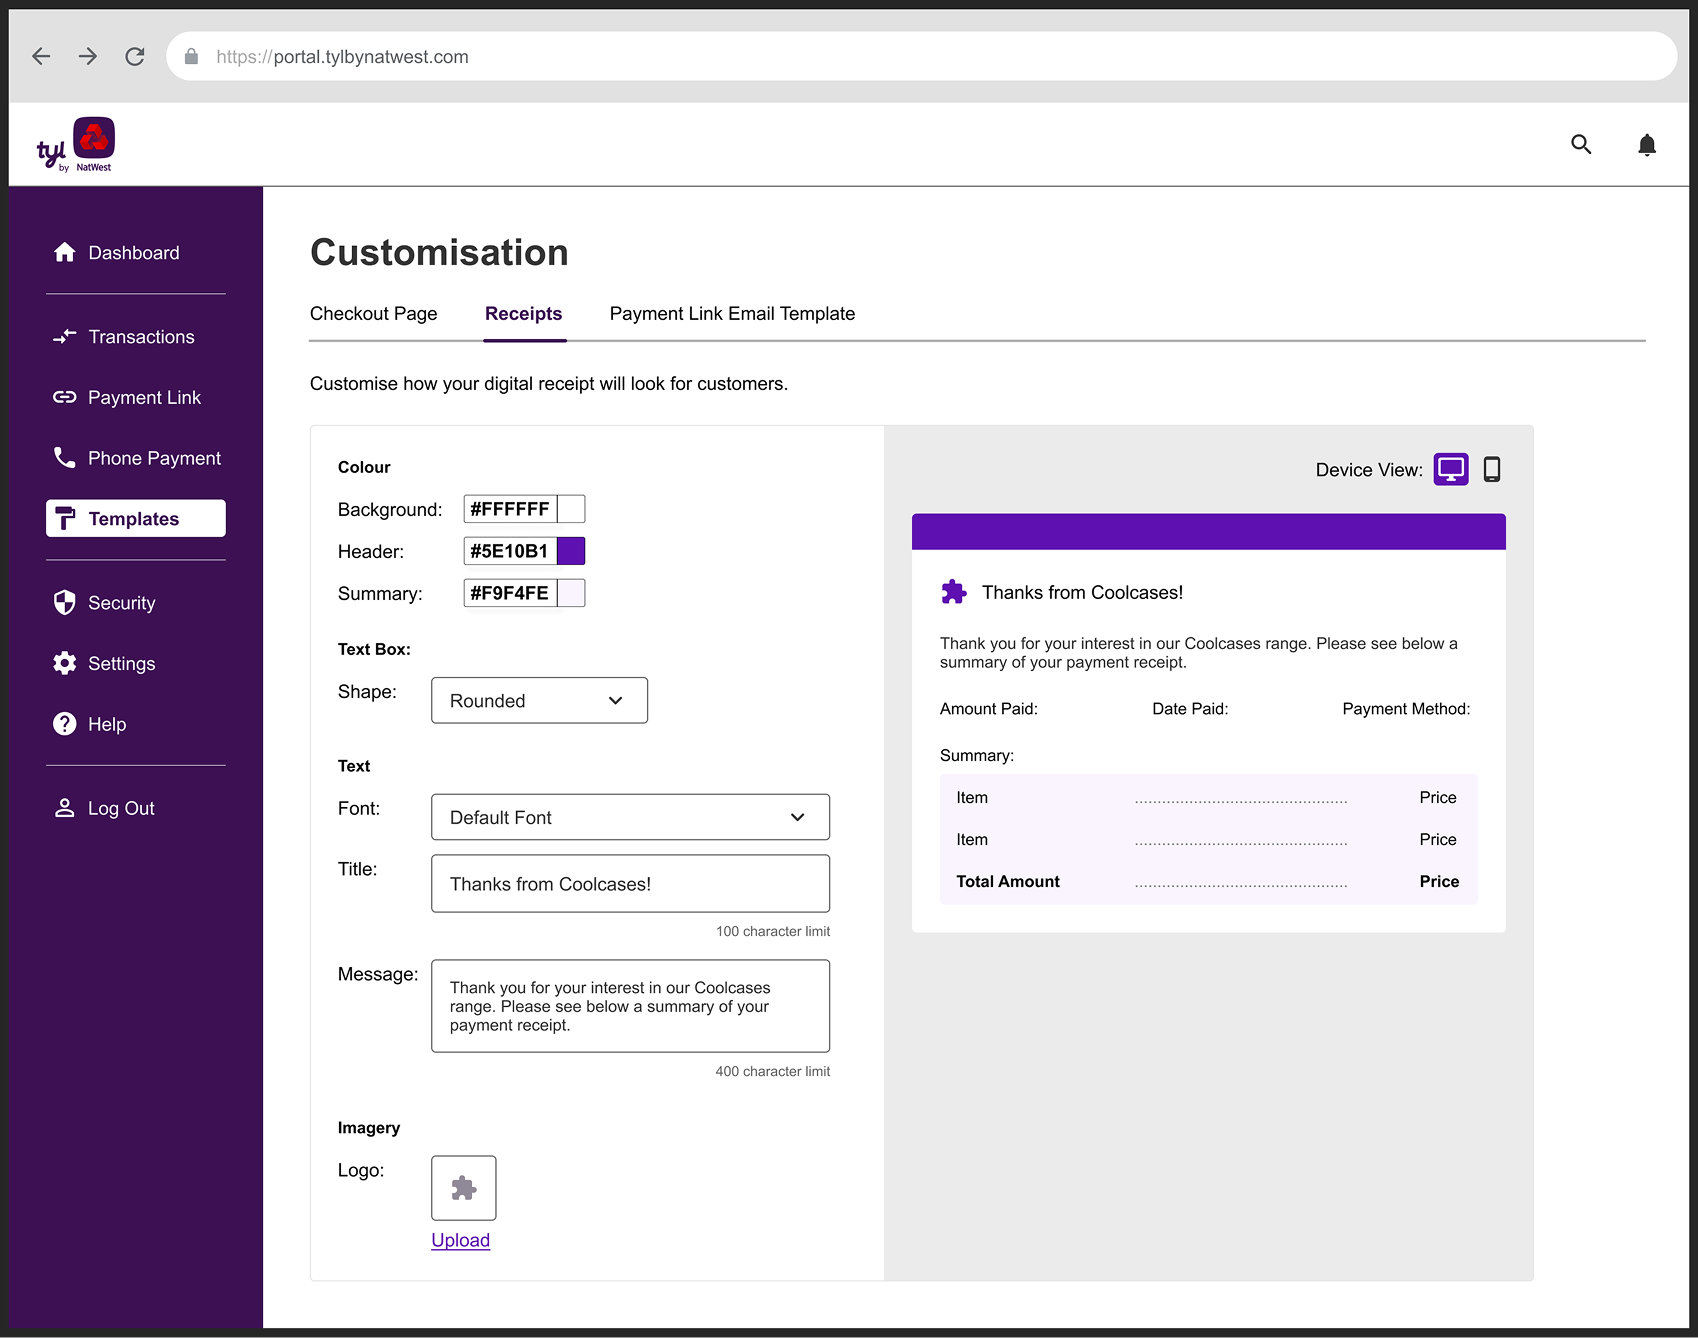
Enable merchants to add their logo, brand colours and itemised order details to payment pages, without needing developer support.
Design
The insights above gave us a clear brief, a product that needed to feel simpler, faster and more trustworthy than anything merchants were currently using.
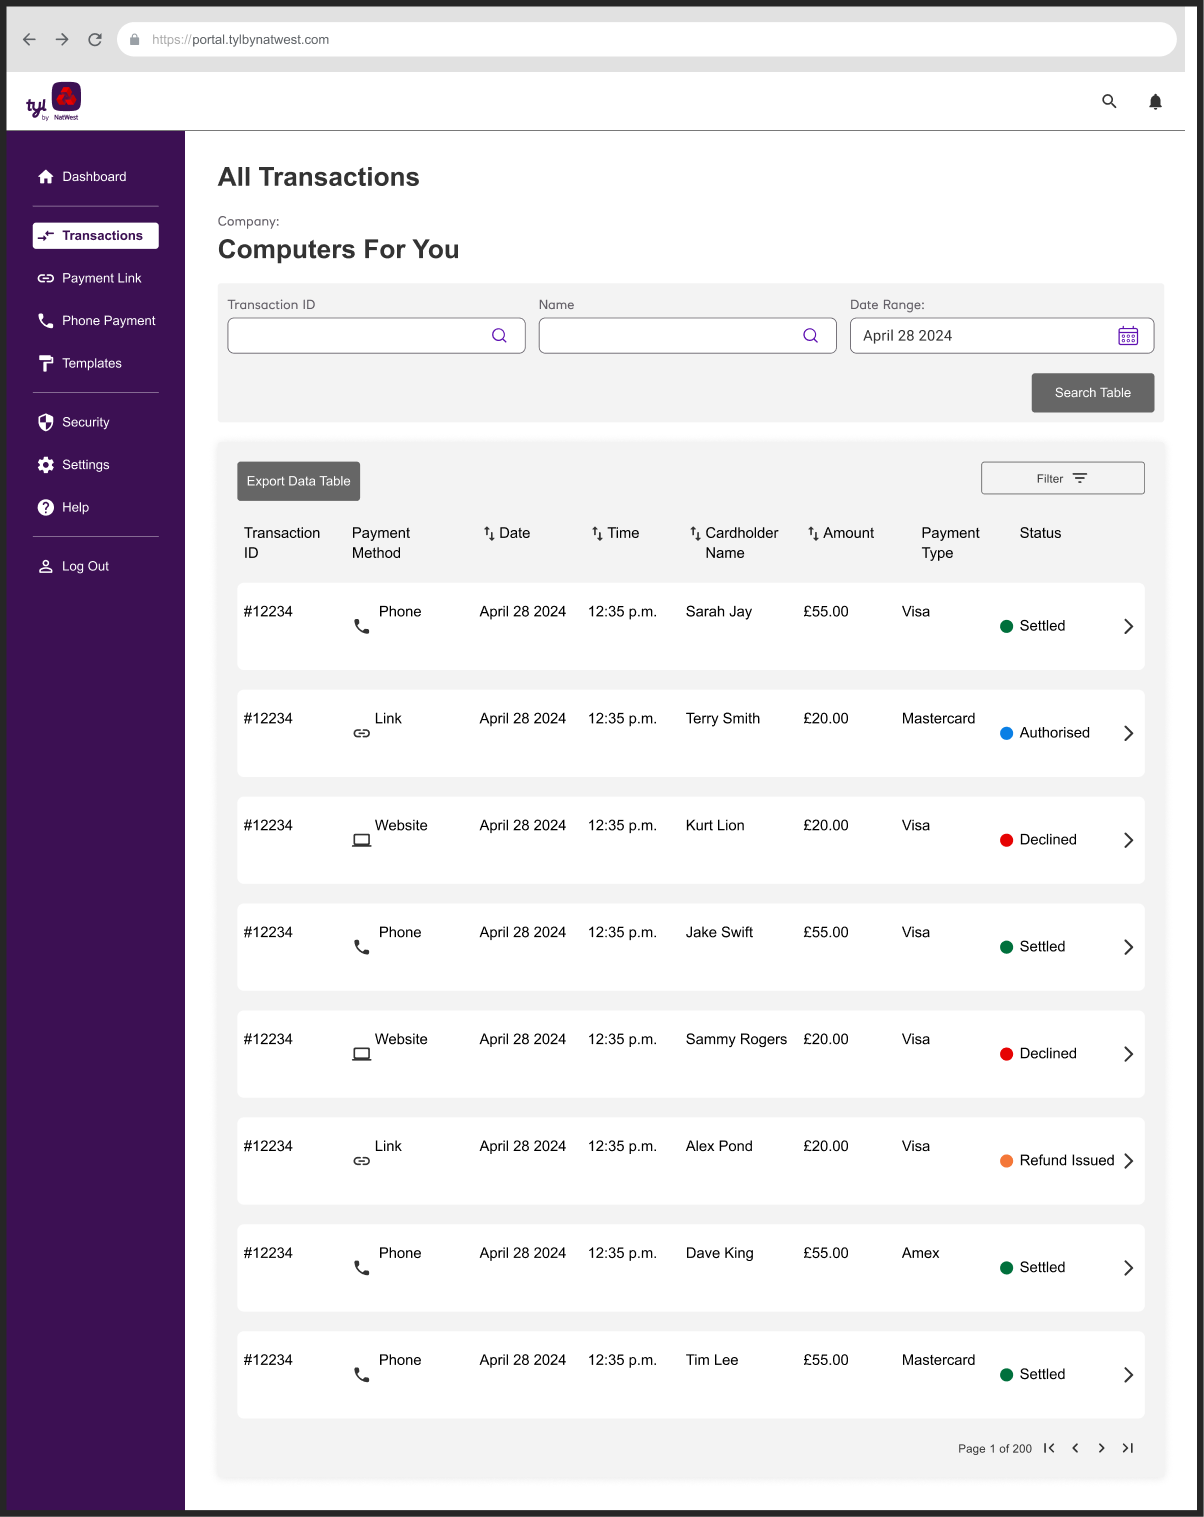
With research complete, I designed a mid-fidelity prototype to test understanding, structure and flow, deliberately avoiding high-fidelity styling so users could focus on the experience rather than the aesthetics.
Three priorities shaped every design decision: reduce cognitive load, build trust, and get merchants to value faster.

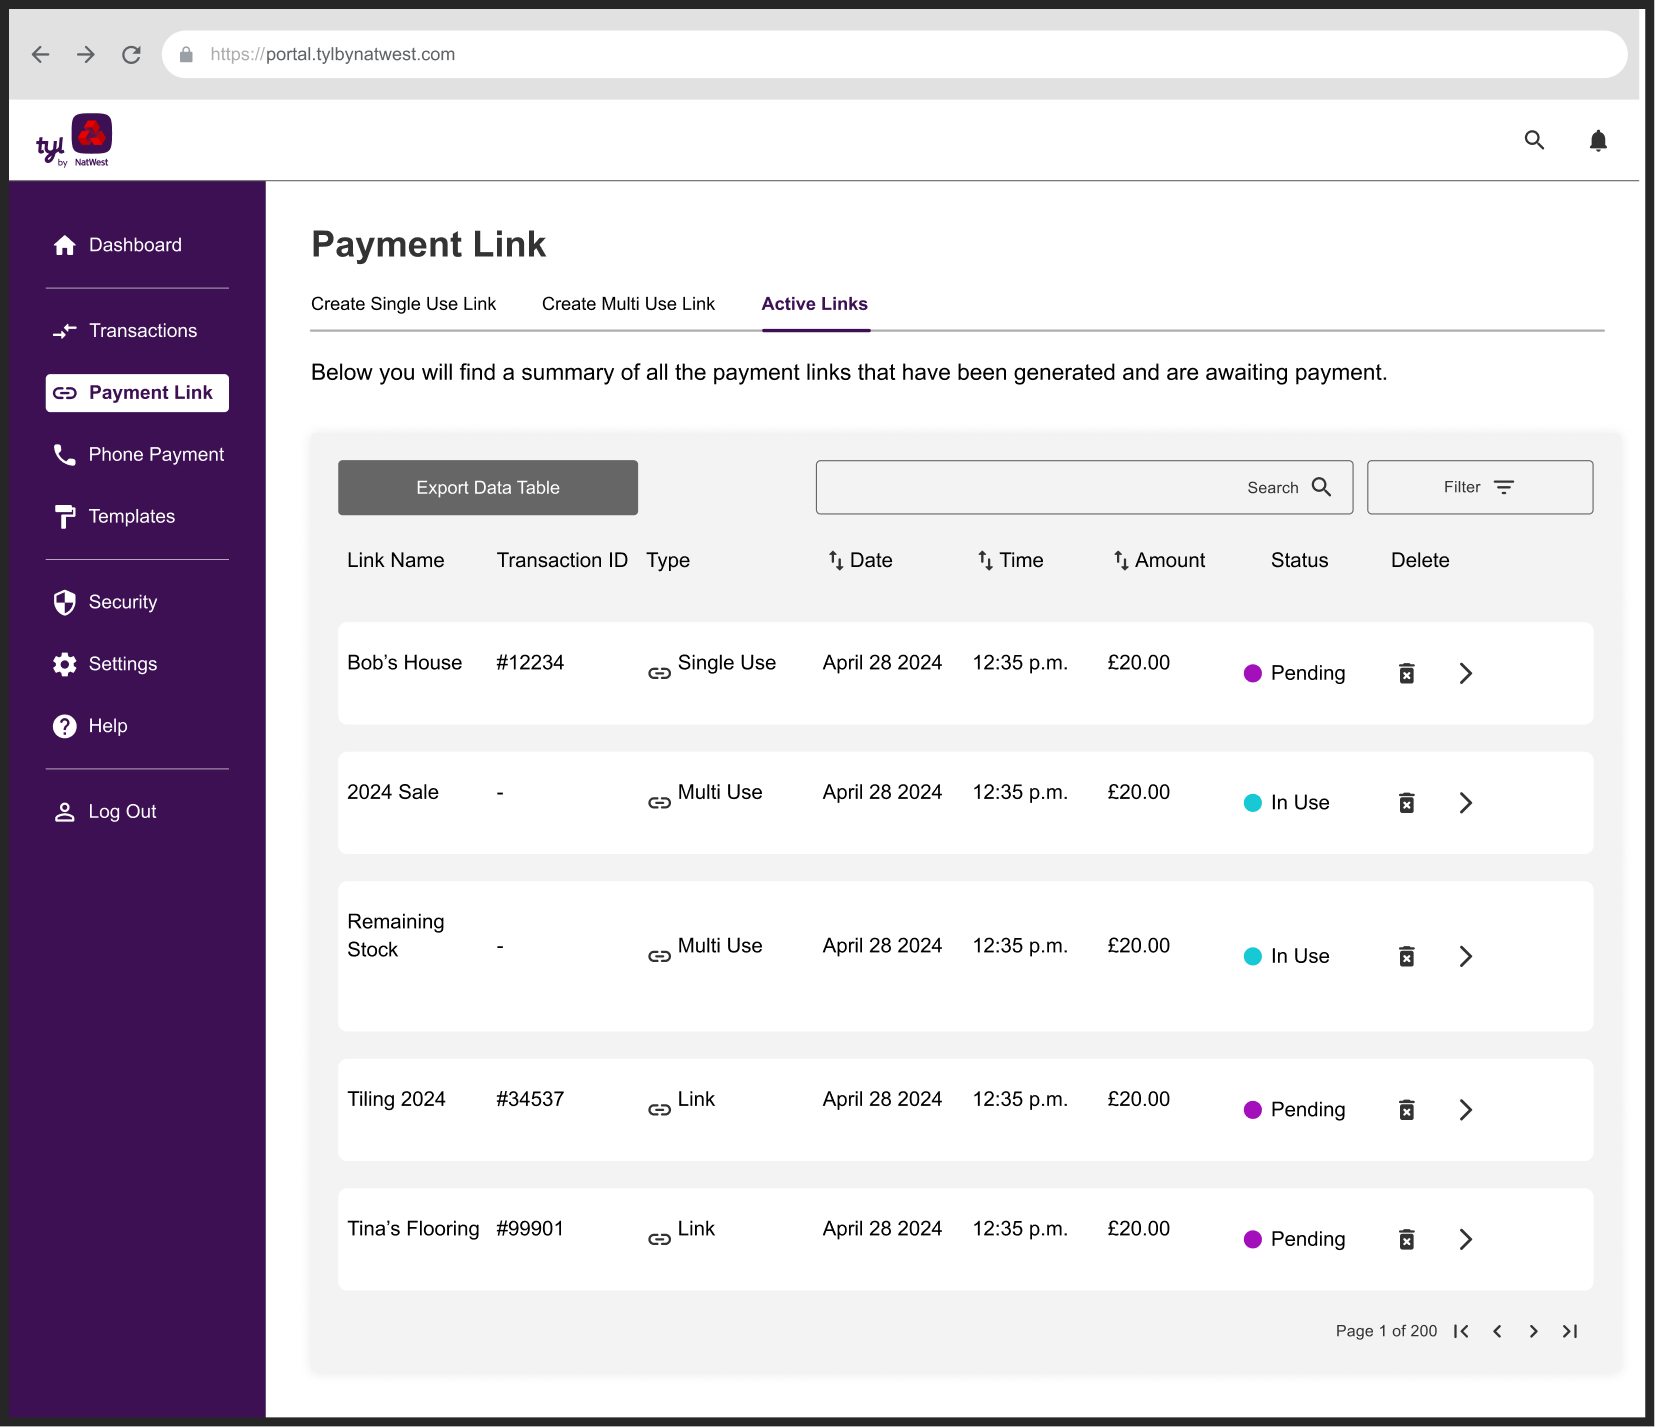
Dashboard as the landing page: The original Virtual Terminal dropped users directly into a phone payment form, a feature most merchants didn't use. Moving the dashboard to the default landing page gave merchants immediate visibility of their transaction activity, mirroring the analytics-first experience they expected from platforms like Stripe and Shopify. This single change re-framed the product from a payment tool into a business management tool.

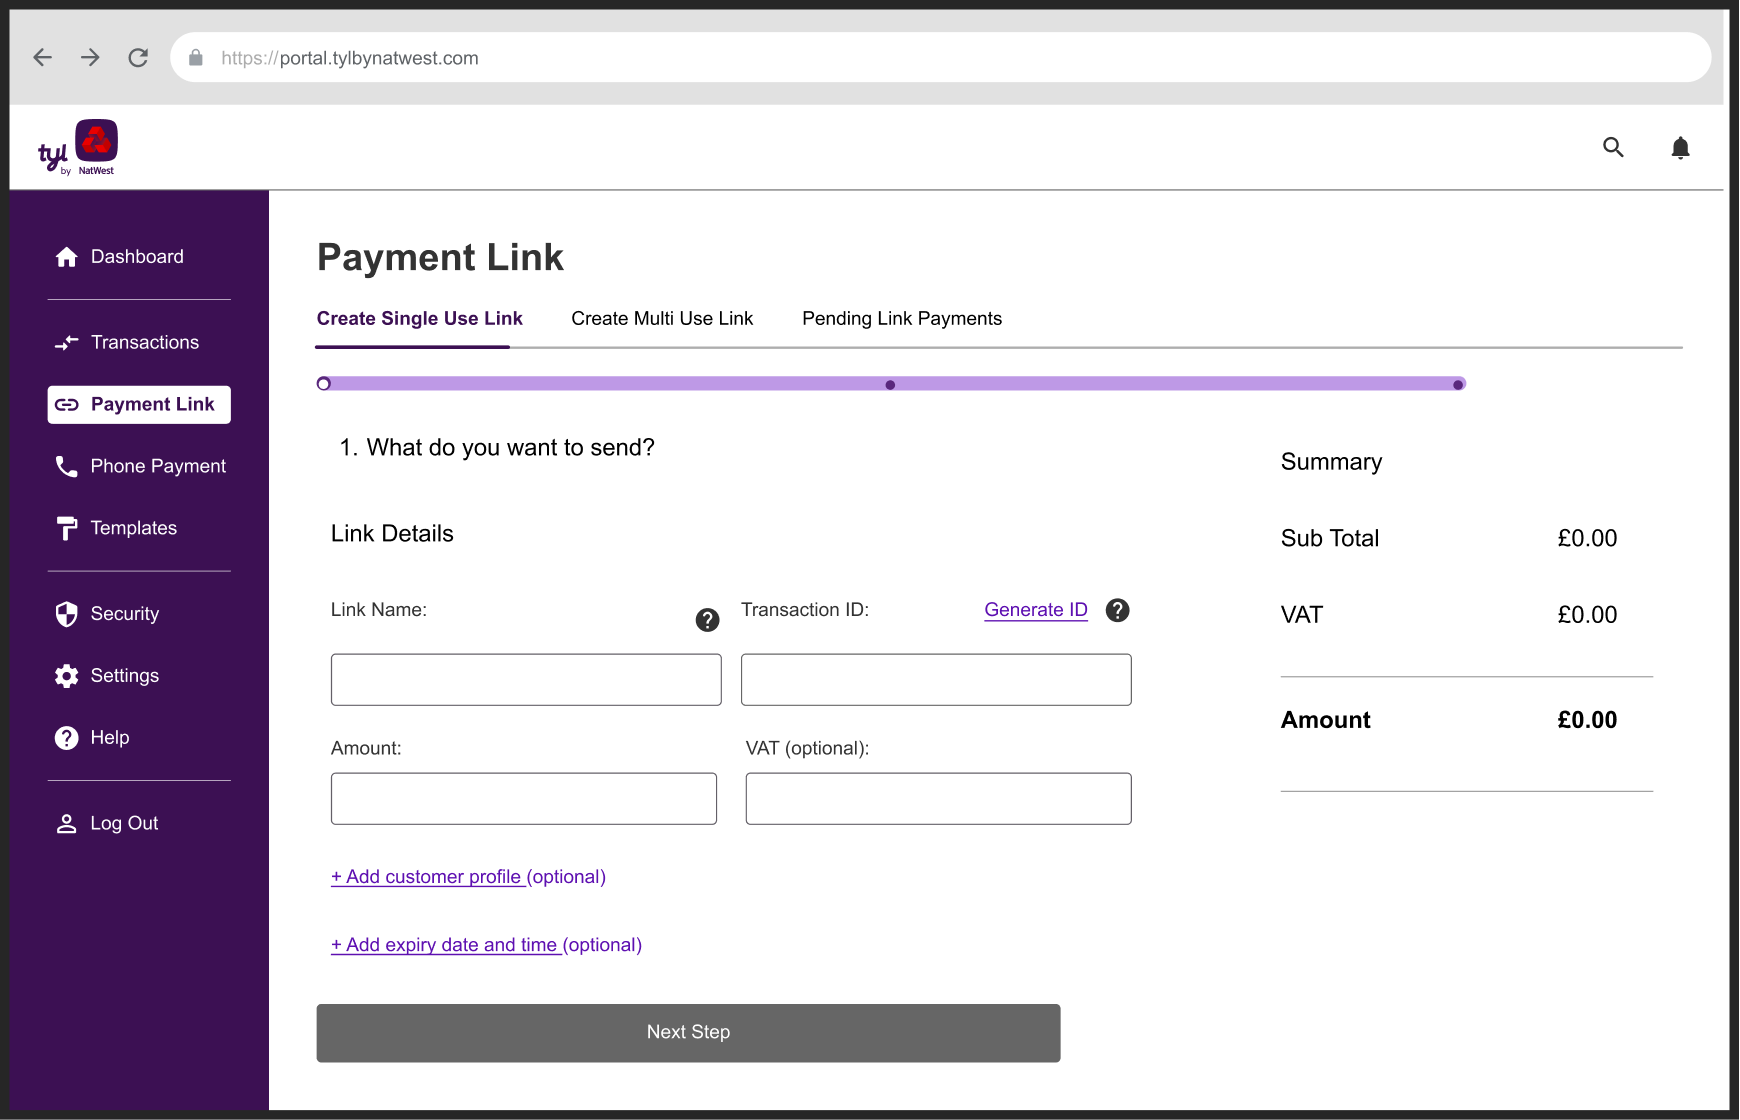
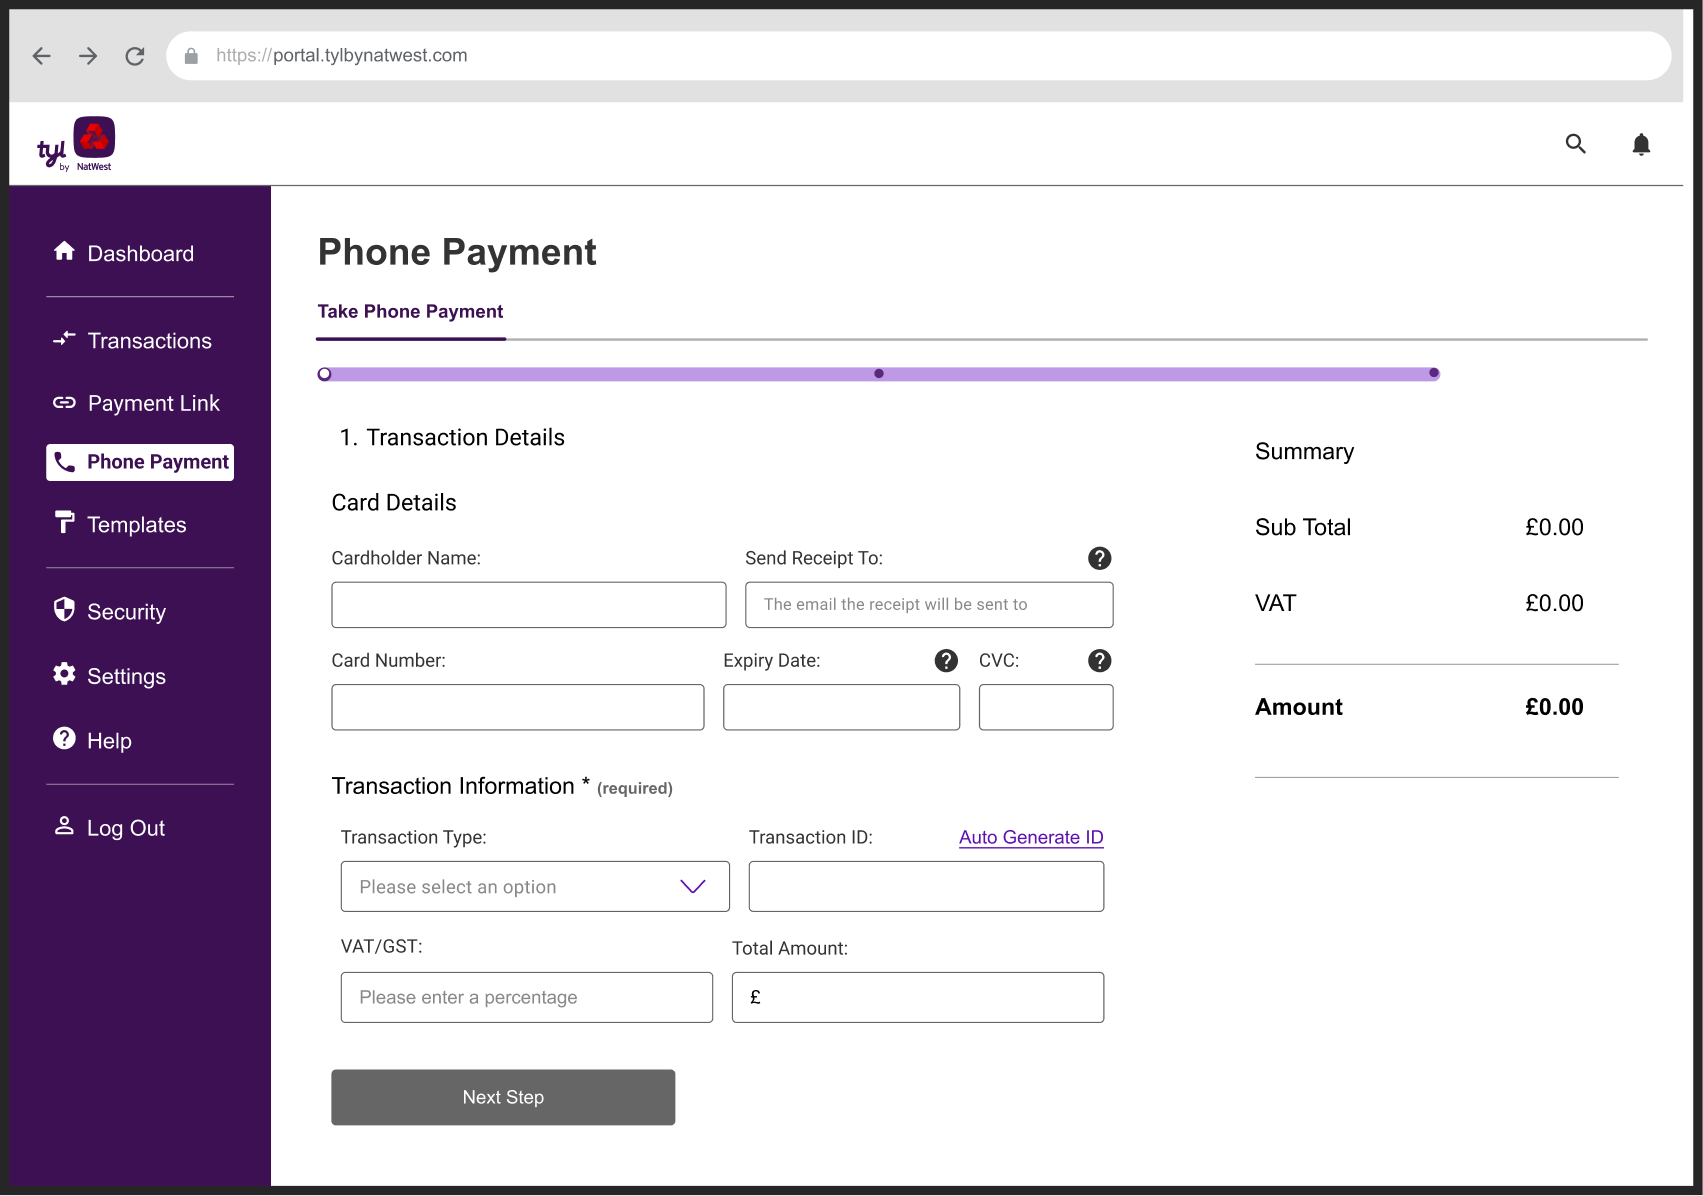
Simplified payment flows: Both the phone payment and pay-by-link flows were restructured to reduce the number of steps and required inputs. Fields were reordered to match the merchant's natural workflow (transaction details first, card or link details second), and IDs were auto-generated to remove unnecessary manual input. Usability testing validated this approach, reducing the time to complete a payment from around 3 minutes to under 1 minute.


Plain language and clear signposting: Every label in the interface was reviewed and rewritten in merchant-friendly language. "Payment URL" became "payment link", ambiguous actions like "completion & return" were removed or clarified, and optional vs required fields were made visually distinct. The goal was to eliminate any moment where a merchant had to stop and think about what the interface was asking of them.


Customisation as a core feature: Rather than treating customisation as an optional extra, it was built into the core payment link and checkout flows. Merchants could add their logo, adjust branding, and include itemised order details, making the checkout feel like a natural extension of their business rather than a generic bank product.


Trust and transparency in payment links: Research flagged that the auto-generated payment URLs looked suspicious to merchants' customers. The redesign introduced a link preview so merchants could see exactly what their customer would receive before sending, addressing the trust issue directly and increasing confidence in the feature.
How Might We:
Deliver
The Virtual Terminal was designed to slot into Tyl's wider portal architecture, moving merchants toward a single unified login across all products. Usability testing focused on the payment link journey (the more complex of the two flows) while the phone payment flow was validated internally.
3 minutes
before
1 minute
after
Payment processing time reduced by over 60%
Merchants could request and receive payments significantly faster, directly addressing the core need identified in research.
Full product ownership
Brought the Virtual Terminal in-house, giving Tyl complete control over the product experience.
Unlocked customer data
Enabled visibility into product usage and merchant behaviour, allowing data-informed decisions going forward.
Unified portal architecture
Integrating seamlessly into Tyl's broader product ecosystem, reducing merchant friction across multiple logins and portals.
The biggest challenge was operating within the constraints of a large, complex organisation. NatWest's scale and regulatory requirements limited our access to customer data and direct user feedback, and navigating that required creativity and persistence rather than conventional research methods.
We made the most of what was available through stakeholder workshops, internal personas and targeted user research. These gave us enough to make confident design decisions. If I were to do anything differently, it would be to invest more time upfront in mapping the broader stakeholder network. With NatWest and Tyl operating in silos, there was likely valuable user insight sitting in parts of the organisation we simply hadn't reached yet.
The research we did conduct was genuinely valuable. Even though participants weren't existing Tyl users, their feedback gave us a sharp picture of where the product was falling short against competitors like Stripe, and that directly shaped our design priorities.